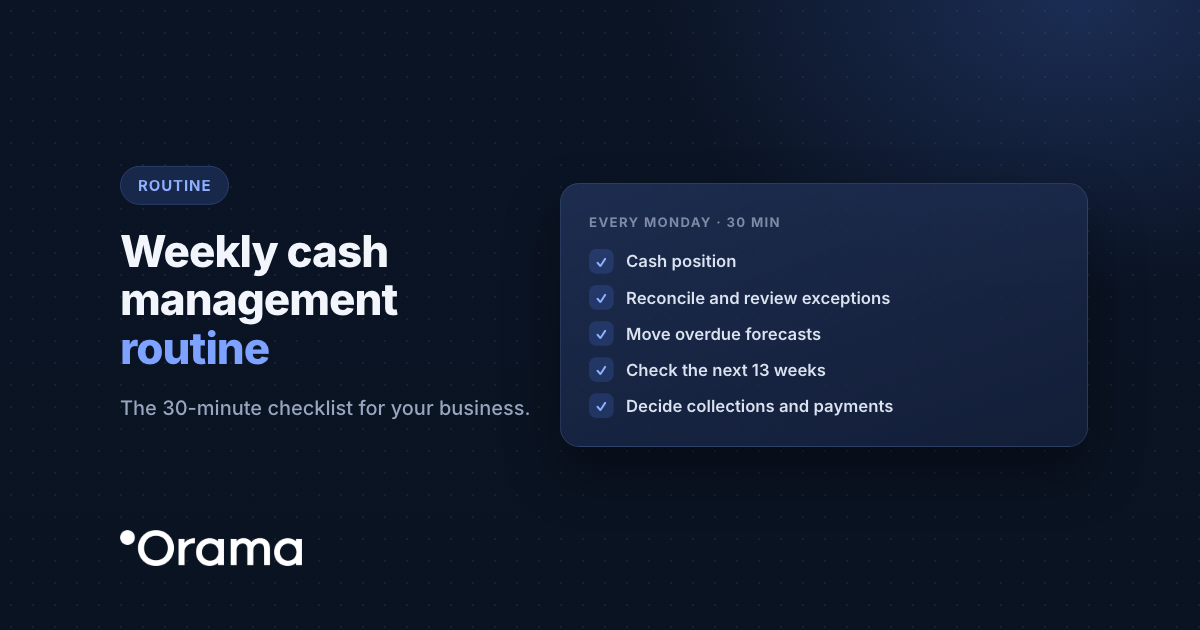
A 30-minute weekly cash management routine is enough to keep a small business’s cash under control: 5 minutes for the cash position, 10 to reconcile and review exceptions, 5 for overdue forecasts, 5 to look at the next 13 weeks and 5 to decide on collections and payments. Add a one-hour monthly review and you are done.
Cash management rarely fails for lack of knowledge. It fails for lack of habit. This is the routine we recommend, with the order, the time for each step and what you need to decide at the end. It is part of our guide to cash management for small businesses.
Before you start: what you need
- A 13-week forecast with your categories of receipts and payments. If you don’t have one, start with the 13-week template.
- A minimum reference balance (your cash buffer): for example, one or two months of fixed payments.
- Access to transactions from all your banks, ideally without downloading statements one by one.
- A fixed day and time in your calendar. Monday morning works well: you decide the week’s payments with an up-to-date picture.
The weekly checklist (30 minutes)
| Step | Time | What you do | What you decide |
|---|---|---|---|
| 1. Cash position | 5 min | Balance of all accounts and available credit on your credit lines | Am I above my buffer today? |
| 2. Reconciliation | 10 min | Assign the week’s transactions to their category and review the ones that have not reconciled automatically | Is there any charge or receipt I didn’t expect? |
| 3. Overdue forecasts | 5 min | Review expected receipts and payments that have not happened and move them to their new date | Which customer do I need to chase? |
| 4. Next 13 weeks | 5 min | Check the lowest forecast balance and the week it happens | Do I need to act? When? |
| 5. Collections and payments | 5 min | Send payment reminders and set the week’s payments | What gets paid, what gets chased, what gets postponed |
1. Cash position (5 minutes)
Write down three figures: balance in your accounts, available credit and the total. Compare them with last week. If the balance has dropped more than expected, you already know where to look in step 2.
2. Reconciliation (10 minutes)
Every bank transaction must be assigned to its category and, where relevant, to the invoice or forecast that explains it. With automatic rules (by description, amount or customer), most transactions reconcile on their own and you only review the exceptions. If you sell online, remember that payment gateway payouts bundle several receipts together.
3. Overdue forecasts (5 minutes)
This is the step people forget most, and the one that improves the forecast most. A receipt expected on Monday that still hasn’t arrived by Friday can’t stay on Monday: move it to the likely date and note it down to chase. We explain how in updating outstanding balances.
4. Next 13 weeks (5 minutes)
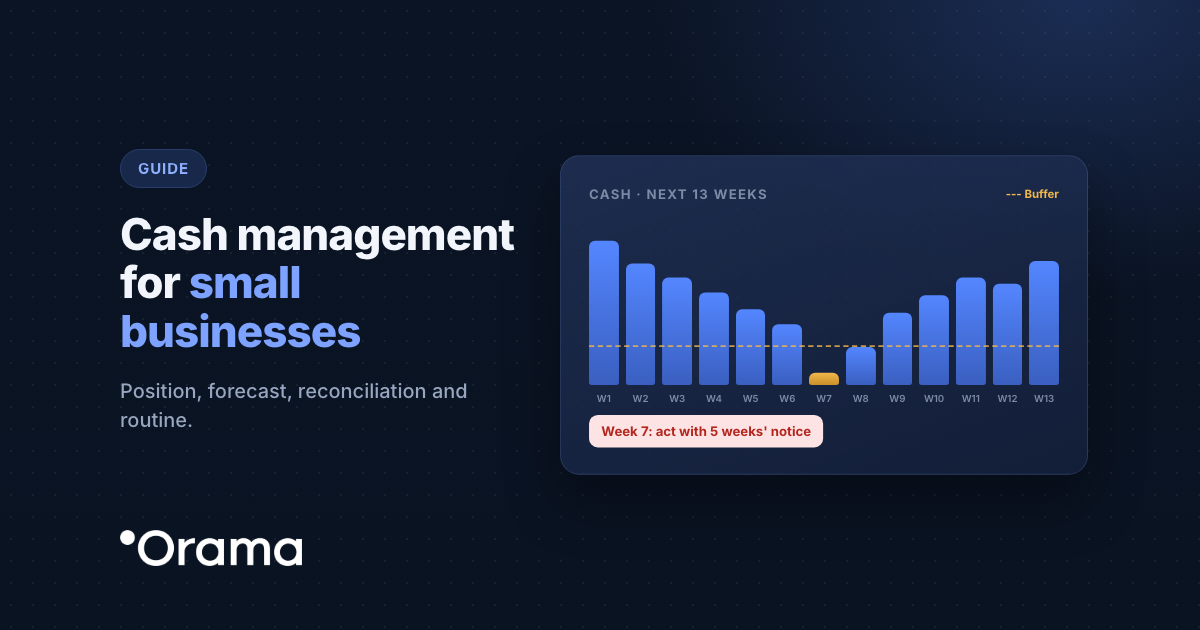
Find the lowest point in the forecast. If the balance drops below your buffer in any week, write it down with the exact figure (“week 7: €18,000 short”). The more weeks’ notice you have, the more options you have, and the cheaper they are.
5. Collections and payments (5 minutes)
With all of the above, decide: which invoices you chase and with whom, which payments go out this week and whether any can be moved within the agreed terms. If the forecast shows pressure, plan now to draw on your credit line for those weeks, not before. To bring late payments down for good, read how to reduce days sales outstanding.
The monthly review (1 hour)
- Forecast vs actual by category: where you got it wrong and why. Correct the estimates that always miss in the same direction.
- 12–24-month forecast: update it with what you know about sales, hiring, investments and taxes. More in annual cash flow forecasts.
- Indicators: days of cash on hand, runway, DSO and DPO, and how they are trending.
- Financing: maturities and renewals of credit lines and loans over the next three months.
- Scenarios: if there is uncertainty (a large customer, an investment), compare a cautious scenario with the base case. We explain it in scenario forecasting.
- Report: a one-page summary for management, partners or your accountant.
Who does it
In a small business, the routine is done by the managing director or the person in charge of admin. In mid-sized companies, admin prepares it and the finance manager reviews it. If you work with an accounting firm, they can do the monthly review with you: we explain how in how an accounting firm can manage its clients’ cash. What matters is having one person responsible and a fixed day.
Anonymised example
A group of two food-industry companies, with €9M in revenue, spent half a morning every Friday logging into five banks, copying balances and updating a spreadsheet. With the banks connected and automatic reconciliation, the routine came down to about 30 minutes on Mondays. Step 3 proved the most useful: by moving overdue forecasts every week, the managing director saw six weeks ahead that a large consumer-goods customer was paying later and later, and negotiated the payment before the summer purchasing peak.
How Orama helps
With Orama, most of the routine is already done when you open it. Balances and transactions from 100% of banks in Spain and 3,000+ across Europe and Latin America update up to 4 times a day, usually 90–99% of transactions reconcile automatically and overdue forecasts are flagged for review. The 13-week view and the 12-, 18- or 24-month forecast recalculate with every transaction. You can also connect our MCP to ask Claude or ChatGPT about your cash. Start your 7-day free trial, no card.