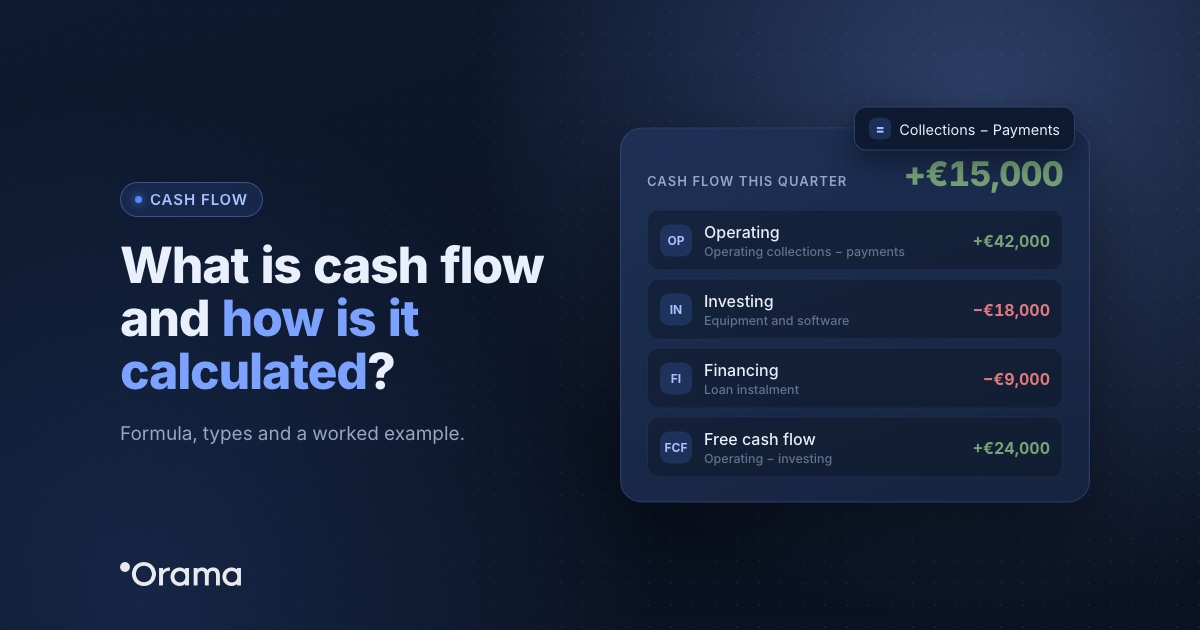
Cash flow is the money that actually comes into and goes out of a company over a period: what has been collected minus what has been paid. It is calculated with the formula Cash flow = Collections − Payments or, if you start from the accounts, approximately with Net profit + Depreciation and amortisation + Provisions.
Unlike profit, which is measured on paper, cash flow tells you how much money you really have to pay salaries, suppliers and taxes. That is why it is the indicator that warns you before a liquidity problem.
How is cash flow calculated?
There are two ways to calculate it. Both are valid, but they answer different questions.
1. Direct method: collections minus payments (the golden rule)
Cash flow = Collections − Payments
Only what has already been collected and what has already been paid counts. It is the reference for managing day-to-day liquidity, because it reflects exactly what has gone through your bank accounts.
The most common mistake: confusing invoicing with cash. A company can invoice a lot, but if its customers pay at 90 days and its suppliers are paid at 30, it can run out of cash even if it is profitable.
2. Indirect method: starting from profit
Cash flow ≈ Net profit + Depreciation and amortisation + Provisions
Depreciation, amortisation and provisions are an accounting expense for the year, but no money actually leaves the bank, so they are added back to profit. This calculation shows the company’s capacity to generate funds through its operations.
Its limitation is the accrual principle: accounting records a sale when the invoice is issued, not when it is paid. If a customer does not pay, the profit is still on paper, but the money is not in the bank, and that can end with you unable to pay your suppliers. For day-to-day cash, the direct method rules.
Types of cash flow and what each one tells you
| Type | How it is calculated | What it tells you |
|---|---|---|
| Operating | Collections from customers − operating payments (suppliers, salaries, taxes, rent) | Whether the business generates cash by itself. It is the most important one. |
| Investing | Proceeds from selling assets − purchases of assets (machinery, software, premises) | How much you invest to grow. It is usually negative in growing companies. |
| Financing | Loans and contributions received − debt repayments and dividends | How you are financed. Positive when funding comes in, negative when you repay. |
| Free cash flow | Operating cash flow − necessary investments | The money really left to repay debt, distribute or save. |
Separating the flows tells you, for example, whether you are looking at a company that is growing and still consuming cash, or at a mature company that funds itself through its own activity.
Anonymised example: one quarter of a services SME
A professional services company with 12 people has this quarter:
- Collections from customers: €310,000
- Payments for salaries, social security, rent, suppliers and taxes: €268,000
- Purchase of equipment and software: €18,000
- Loan instalment: €9,000
| Item | Amount |
|---|---|
| Operating cash flow (310,000 − 268,000) | +€42,000 |
| Investing cash flow | −€18,000 |
| Financing cash flow | −€9,000 |
| Total cash flow for the quarter | +€15,000 |
| Free cash flow (42,000 − 18,000) | +€24,000 |
In that same quarter the company invoiced €360,000: €50,000 has been invoiced but not yet collected. In the profit and loss account the quarter looks good; in cash, the margin is tighter. That is why you should look at both.
Positive and negative cash flow: how to read them
Positive means more money came in than went out in that period. The surplus can be reinvested, used to repay debt or kept as a buffer. But it is not the same as profit: a company can be profitable without generating cash in a period, and generate cash without being profitable.
Negative means you are spending more than you generate. A negative month due to an investment is normal; if operating cash flow is negative month after month, the company will end up needing financing. Always check which of the three flows it comes from.
Common mistakes when calculating cash flow
- Counting issued invoices as if they had been collected. Cash flow only includes real collections.
- Forgetting payments that are not monthly: quarterly VAT, extra salary payments, annual insurance or corporate tax.
- Mixing the three flows and not seeing that positive cash comes from a loan rather than from operations.
- Only looking at the past. Historical cash flow explains what happened; a forecast tells you what is going to happen.
- Reviewing it once a quarter. When cash is tight, you need to check it every week.
Cash flow vs profit
Profit measures whether the business is profitable; cash flow, whether it can pay its bills on time. A profitable company can close for lack of liquidity, and a loss-making company can hold on if it has cash. We explain it in more detail in why cash is more important than profit.
From calculating cash flow to forecasting it
Cash flow is not only for looking back. If you project it, you will know in advance when you could run out of liquidity and you can act in time: renegotiate terms, adjust spending or apply for financing without rushing. Two useful indicators to start with are days of cash on hand and your runway. For the medium term, see how to build an annual cash flow forecast.
How to improve cash flow when cash is tight
- Shorten collection periods and follow up on outstanding invoices.
- Renegotiate payments with your suppliers and consider early payment discounts when your cash allows it.
- Limit expenses that are not essential.
- Include every change in your forecast to see its real effect on your cash over the coming months.
Control your cash flow with Orama
With Orama you connect your banks (100% of banks in Spain and 3,000+ across Europe and Latin America), which are updated up to 4 times a day, and Orama automatically reconciles between 80% and 95% of transactions. From there you see your real cash flow and forecast it 12, 18 or 24 months ahead, with scenarios to make decisions.
Try Orama free for 7 days, no card required or book a 30-minute demo.
Frequently asked questions
Keep reading: you may also want to see when a spreadsheet is enough and when you need treasury software and what treasury software for an SME should include.
What is cash flow in a nutshell?+
What does positive cash flow mean?+
Is negative cash flow bad?+
How is free cash flow calculated?+
What is the difference between cash flow and liquidity?+
How often should I review cash flow?+
📊 Free Excel template
Still doing your cash forecast by hand? Get the 13-week cash flow forecast template (in Spanish). Download the free template →